
Case Background
The petitioner was an Executive Engineer in the Rural Works Department of the Government of Bihar. He superannuated from service on 30.09.2020.
After his retirement, he claimed that his retiral benefits and other dues, including arrears of salary for a particular period, had not been properly paid. Because of this, he filed a writ petition before the Patna High Court seeking directions against several authorities, including the State of Bihar, the Principal Accountant General (A and E), the Secretary, Rural Works Department, the Patna Municipal Corporation, the Treasury Officer and the Director, Group Provident Fund.
During the pendency of the writ petition, the situation changed. According to the petitioner’s own advocate, all substantive retiral benefits and most dues were eventually released. However, disputes remained on three points: interest for delayed payment of retiral benefits, alleged short payment under the General Provident Fund (GPF) account, and alleged payment of a lower pay scale during his deputation to Patna Municipal Corporation.
What the Court Examined and Decided
Justice Harish Kumar heard arguments from the petitioner’s side and from counsels representing the State, Patna Municipal Corporation and the Accountant General.
First, the Court recorded the admitted position: during the pendency of the writ petition, all major retiral benefits and other dues were paid to the petitioner. The remaining dispute related primarily to interest and certain calculations, not non‑payment of the benefits themselves.
Claim for interest on delayed retiral benefits
The petitioner’s counsel stated that though the petitioner retired on 30.09.2020, actual payment of retiral benefits was made only on 25.05.2021. According to him, this meant a delay of 237 days.
On this basis, he claimed that the petitioner was entitled to at least statutory interest for the delayed period. However, the judgment does not mention that any specific statute or rule was cited, nor any rate of interest. The Court also did not itself compute or accept any specific figure.
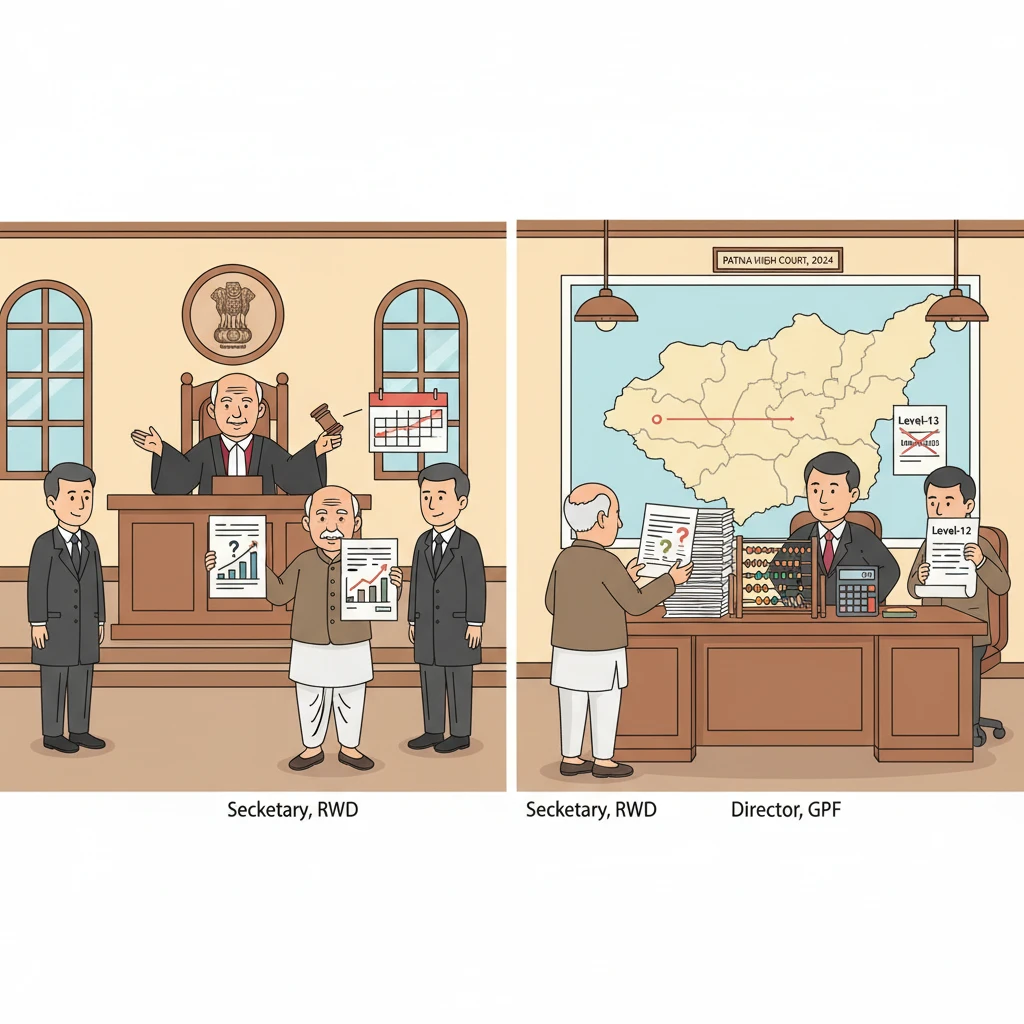
Instead, for the grievance regarding interest, the Court granted liberty to the petitioner to raise this claim before respondent no. 3, i.e., the Secretary, Rural Works Department. The Court directed that this authority would consider the claim for interest and pass an appropriate order. Thus, the question of whether interest is legally payable, and at what rate, was left to the departmental authority to decide in the first instance.
Dispute over GPF calculation
The second dispute concerned the petitioner’s GPF account. According to the petitioner’s counsel, the respondent authorities had paid GPF of Rs. 28,54,785/‑. But the petitioner’s own calculation allegedly showed that the correct amount should be Rs. 29,13,730.36.
On this basis, the petitioner claimed he was entitled to the remaining amount, along with interest. The Court did not verify or endorse either figure. Instead, it treated this as a dispute confined to calculation of the GPF amount, which needed to be examined by the concerned GPF authority.
The Court therefore gave liberty to the petitioner to file a representation before respondent no. 6, i.e., the Director, Group Provident Fund, Pant Bhawan, Patna. The petitioner was permitted to attach his own calculation chart with this representation.
The Director, Group Provident Fund, was directed to verify the petitioner’s claim and, after proper examination, dispose of the representation. The Court set a time frame: preferably within eight weeks from the date of receipt or production of a copy of the Court’s order.
The Court further clarified that if, upon such examination, the petitioner’s claim was found to be correct, the necessary payment must be made to him. This ensures that the petitioner has a clear administrative route for redressal while also placing a time limit on the department.
Alleged payment of lower salary during deputation
The third issue raised related to the petitioner’s deputation to Patna Municipal Corporation. The petitioner had been working as an Executive Engineer in the Rural Works Department when he was deputed to Patna Municipal Corporation.
He remained on deputation there from 15.09.2018 to 03.07.2020. The petitioner claimed that he had been granted the pay scale of Level‑13 with effect from 13.05.2018 by Government Circular/Letter dated 20.11.2019. A copy of this circular was brought on record as Annexure‑12 to a supplementary counter affidavit.
Despite this, according to the petitioner, he was paid salary only in the pay scale of Level‑12 for the period he worked in Patna Municipal Corporation. This alleged short payment formed part of his grievance in the writ proceedings.
On behalf of the Patna Municipal Corporation, counsel responded that the original writ petition had no mention or “whisper” of this grievance regarding lower salary. The issue of wrong pay scale was being raised for the first time only through a supplementary affidavit.
Nevertheless, counsel for the Municipal Corporation fairly stated that if the petitioner had any such grievance, he could file a representation before the Municipal Commissioner, Patna Municipal Corporation. The Municipal Commissioner would then examine and consider the grievance and pass an appropriate order, preferably within eight weeks.
The Court accepted this position. It did not give any direct finding on whether the petitioner was in fact entitled to Level‑13 pay during his deputation period. Instead, it acknowledged that this was a new factual dispute requiring examination by the Municipal Corporation itself.
Thus, the Court granted liberty to the petitioner to approach the Municipal Commissioner with a representation regarding alleged less payment of salary. The Municipal Commissioner was directed to examine and consider the grievance and pass appropriate orders preferably within eight weeks, echoing the time frames fixed for the GPF and interest claims.
Overall disposal of the writ petition
After giving these directions, the Court concluded that the writ petition stood disposed of. No further relief was granted at this stage. The Court did not award costs, nor did it record any finding that the authorities were at fault or guilty of delay; such issues, particularly regarding interest, were left to be examined by the competent authorities.
In effect, the Patna High Court treated the case as one where primary dues had been paid but calculation‑related disputes and an interest claim remained. Rather than itself carrying out detailed accounting, the Court channelled the petitioner towards the appropriate administrative forums but ensured time‑bound decisions.
Why This Judgment Matters
This judgment is important for retired government employees who face delays or discrepancies in their retirement benefits.
First, it shows that even after filing a writ, if major dues are released during the case, the High Court may not itself decide the remaining calculations. Instead, it may direct the employee to raise detailed disputes before the specialised authorities, such as the GPF Director or departmental head.
Second, the order confirms that if an employee feels he was not given the correct pay scale, especially while on deputation, the proper course is first to approach the concerned employer—in this case, the Municipal Commissioner. Only after such representation and decision would a further legal challenge usually arise.
Third, the Court emphasised time‑bound action. For each of the petitioner’s surviving grievances—GPF calculation, salary during deputation, and interest for delayed payment—the authorities were told to decide “preferably within eight weeks”. This offers some protection against indefinite delay once a representation is filed.
For similarly placed retirees in Bihar, the message is clear: gather your documents, prepare a calculation chart where needed, and file detailed representations before the particular authorities responsible for GPF, salary fixation and interest. The Patna High Court can then be approached, if necessary, after those authorities have taken or refused to take action.
Legal Issues and Answers
-
Issue: Whether the Patna High Court would itself compute and order payment of alleged short GPF amount, higher pay scale salary, and interest on delayed retiral dues after the main benefits had been released.
Answer: The Court declined to carry out these calculations directly and instead directed the petitioner to file representations before the Director, Group Provident Fund (for GPF), the Municipal Commissioner, Patna Municipal Corporation (for alleged lower salary), and the Secretary, Rural Works Department (for interest), who must examine the claims and pass appropriate orders within a reasonable, preferably eight‑week, period.
Cases Cited by the Court
- No prior judgments or case law have been cited or relied upon in the text of this decision.
Case Details
Case Number: Civil Writ Jurisdiction Case No. 5053 of 2022
Case Title: Arun Kumar Singh v. The State of Bihar & Ors.
Coram: Hon’ble Mr. Justice Harish Kumar
Citation: 2024(1) PLJR 642
Advocates:
- For the petitioner: Mr. Bishwajeet Kumar, Advocate
- For the State of Bihar: Mr. Shiv Kumar, AC to GA 3
- For Patna Municipal Corporation: Mr. Ranjeet Kumar Pandey, Advocate
- For the Accountant General: Mr. Arun Kumar Arun, Advocate
Nature of the case: Civil writ petition seeking directions for payment and proper calculation of retiral benefits, GPF and salary, along with interest for delayed payment, after superannuation from government service.
Link to the Judgment: Click here to view the official Patna High Court judgment
If you found this explanation helpful and wish to stay informed about how legal developments may affect your rights in Bihar, you may consider following Samvida Law Associates for more updates.







