
Case Background
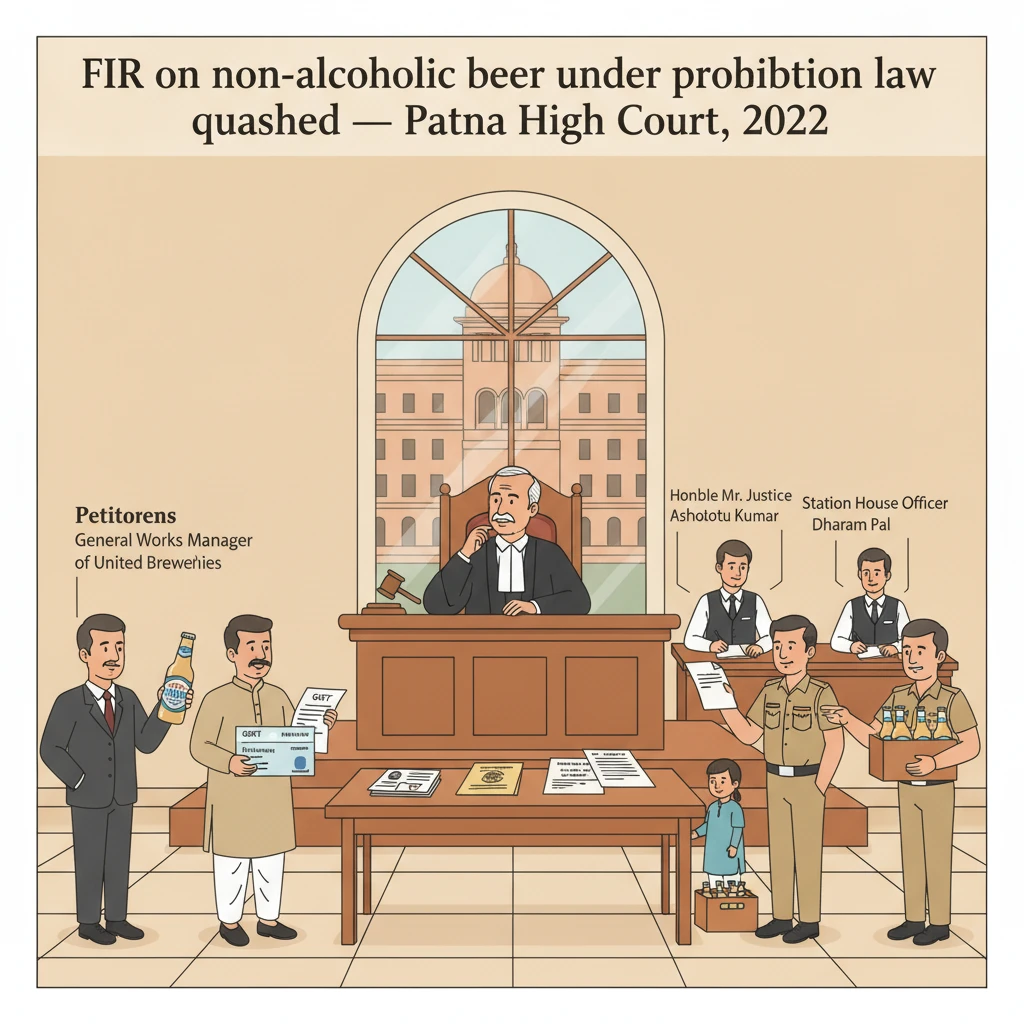
The dispute began on 12.10.2020 in Madhubani district. A police officer named Niranjan Kumar Singh brought 24 bottles of “Ultra” non-alcoholic beverage of Kingfisher company, each of 300 ml, to the Madhubani Town Police Station. These bottles had been seized from one Jiwach Kumar, and a station diary entry (No. 452 of 2020) was made on the same date.
The Station House Officer, Dharam Pal, later recorded his self-statement on 14.10.2020. He stated that senior officers were informed and he was directed to get the liquid tested by the Excise Department.
The sealed bottles were first sent to the Superintendent of the Excise Department at Madhubani. However, they were returned because there was no testing facility there. A request was made to send the samples to the Chemical Examiner of the Excise Department at Patna.
On 13.10.2020, the samples were sent to the Chemical Inspector of the Excise Department, Patna. The analysis report, received on the same date, stated that the sample liquid was a fermented liquor with 0.8% v/v ethyl alcohol. It was said to be in breach of the Bihar Prohibition and Excise Act, 2016.
Police then interrogated Jiwach Kumar. He disclosed that the bottles belonged to one Shankar Santhalia of Madhubani, for whom he worked as a salesman. On his employer’s instructions he had brought the bottles and was then caught by the police.
According to the statement, Shankar Santhalia had purchased the bottles from M/s Ma Enterprises, Madhubani. The proprietor of this firm is Mukesh Kumar, the petitioner in Criminal Writ Jurisdiction Case No. 157 of 2021.
Jiwach Kumar was taken into custody and later Shankar Santhalia was also arrested. It was then alleged that these persons, along with the manufacturing unit of United Breweries Limited at Naubatpur, Patna, its management and workforce, had committed cognizable offences under various sections of the Indian Penal Code and the Bihar Prohibition and Excise Act, 2016.
On this basis, Madhubani Town P.S. Case No. 265 of 2020 dated 14.10.2020 was registered under Sections 30(a) and 35(e) of the Bihar Prohibition and Excise Act, 2016 and Sections 272, 273, 465 and 420 of the Indian Penal Code.
United Breweries Limited, a company incorporated under the Companies Act, 1956, runs a brewery at Naubatpur, Patna which manufactures non-alcoholic beers/drinks. In Criminal Writ Jurisdiction Case No. 89 of 2021, the manufacturing unit was represented by its General Works Manager, Brewery.
The petitioner in Criminal Writ Jurisdiction Case No. 157 of 2021, Mukesh Kumar, is the proprietor of M/s Ma Enterprises, Madhubani. He was said to have purchased the non-alcoholic drinks through GST invoices for sale in Madhubani and to hold a licence under the Food Safety Act for sale of such beverages.
What the Court Examined and Decided
The core challenge before the Patna High Court was to the very foundation of the prosecution. The petitioners argued that, on the admitted facts, none of the offences under the Indian Penal Code or the Bihar Prohibition and Excise Act, 2016 was made out.
For the company, it was submitted that it had never manufactured or sold any intoxicant or liquor as defined in the Excise Act. The product involved was a malt-based non-alcoholic beverage marketed under the brand names “Kingfisher Radler” and “Kingfisher Ultra”.
The company stated that it is in the business of manufacturing alcoholic beverages and beer but, after prohibition on sale and consumption of foreign liquor and beer in Bihar from 05.04.2016, it sought specific permission from the Excise and Prohibition Department to manufacture malt-based non-alcoholic drinks.
On such request, the Excise Commissioner, Bihar, granted a licence on 13.12.2016. Further, by notification dated 24.01.2017, the company was permitted to engage in the manufacture of non-alcoholic beverages.
The company also pointed out that it had obtained a licence from the Food Safety and Standards Authority of India (FSSAI) for manufacture and sale of non-alcoholic beverages and followed the standards prescribed by the Bureau of Indian Standards (BIS). As per BIS specifications, a non-alcoholic beverage should contain less than 0.5% ethyl alcohol by volume.
The petitioners produced material showing that samples from the same batch manufactured at their brewery had been tested at the CSIR–Central Food Technological Research Institute, Mysore, a Government laboratory recognised as a Food Safety and Analytical Quality Control Laboratory. That report stated that the drink was zero per cent alcohol based.
They also relied on tests conducted by two National Accreditation Board approved testing and calibration laboratories, Intertek India Private Limited and Vimta. These laboratories similarly reported zero per cent alcohol in the samples.
The petitioners highlighted that even the same Chemical Examiner of the Excise Department, who had given the 0.8% v/v report in this case, had in relation to another sample of the same product found only 0.4% v/v ethyl alcohol.
On learning of that prosecution, the company had requested the Excise Commissioner to get the samples tested in another NABL accredited laboratory with facilities to test alcoholic beverages in accordance with FSSAI guidelines. This request, according to the petitioners, was ignored.
On the legal side, counsel for the company drew attention to the definitions in the Bihar Prohibition and Excise Act, 2016. Sections 2(40) and 2(44) define “intoxicant” and “liquor”. Sections 2(4) and 2(6) define “alcoholic beverage or portable liquor” and “BIS Standards”.
Based on a combined reading of these provisions, it was argued that an “intoxicant” must be liquor served as alcohol or as a substitute for alcohol and consumed for the purpose of intoxication. If the beverage is not sold or used for intoxication and falls within BIS standards for non-alcoholic drinks, then it should not attract penal provisions of the prohibition law.
The petitioners contended that even if, for the sake of argument, the seized sample actually had more than 0.5% v/v ethyl alcohol, there was no allegation that it was consumed or sold as an intoxicant. There could be many reasons for a slightly higher reading, such as further fermentation of the sample or of the bottle over time. Without investigating these possibilities, the authorities had mechanically launched prosecution.
They also placed reliance on an earlier decision of the Patna High Court in M/s Smart India Marketing v. State of Bihar (Cr. WJC No. 627 of 2017, decided on 05.11.2017). In that case, the Court had quashed an FIR and held that the Prohibition Act does not prohibit sale of non-alcoholic substances that conform to BIS standards defined under the Act.
The judgment in Smart India Marketing further held that, to attract penal provisions such as Section 30(a) and 30(g) of the Act, the substance must be an intoxicant or liquor that can be served as alcohol or as its substitute and is capable of being used for getting intoxicated.
The petitioners argued that the laboratory report of the Excise Chemist, being the sole foundation for this prosecution, was suspect. FSSAI, they said, has prescribed standard guidelines for detecting ethyl alcohol content in beverages, and these had not been followed by the Excise lab. Therefore, the report was described as a “hasty conclusion” that should not be treated as sacrosanct.
The Court then examined the testing standards. It noted that the Bureau of Indian Standards has issued a second revision of methods of test for alcoholic drinks, providing three methods for determination of ethyl alcohol content: a routine method for testing apparent strength, a referee method for testing real strength, and a third method for drinks that yield volatile oil on distillation.
These BIS methods specify the apparatus, testing procedure, and calculation formulae. The Court found that there was nothing on record to show that the Excise Department’s Chemical Examiner had followed these prescribed processes. Therefore, his report was not fit to be treated as a final basis for launching prosecution.
The Court then turned to the law on quashing FIRs. It cited the Supreme Court’s decision in State of Haryana v. Bhajan Lal, Supp (1) SCC 335, which gives illustrative situations where a High Court can quash an FIR under Article 226 of the Constitution or Section 482 CrPC. One such situation is where the allegations in the FIR, even if taken at face value and accepted entirely, do not prima facie constitute any offence or make out a case against the accused.
The Court also referred to the recent Supreme Court decision in Neeharika Infrastructure Pvt. Ltd. v. State of Maharashtra, 2021 SCC OnLine SC 315. That judgment reiterated that investigation should not ordinarily be interfered with and that the power to quash an FIR must be used sparingly and with care.
Applying these principles, the Patna High Court examined whether the facts alleged in this case showed any offence. The prosecution was built solely on the finding that some seized samples had ethyl alcohol content marginally above the tolerance limit.
The Court observed that if the seized articles were not sold as intoxicants or capable of being consumed as intoxicants, they would not fall within the category of liquor prohibited under the Act. It recognised that a “margin of error is inherent in such strict legislation”.
The Court held that the facts did not warrant prosecution of the petitioners. There was no indication of intention on their part to breach excise law. It emphasised that there is no prohibition on the sale of non-alcoholic beverages in Bihar.
The Court reminded that the object and purpose of the Bihar Prohibition and Excise Act, 2016 is to enforce and promote complete prohibition of liquor and intoxicants in the State and matters connected with that. A minor infraction in ethyl alcohol content of a non-alcoholic beverage like fruit beer does not offend this object and purpose.
It described as “highly unreasonable” any conclusion that a minor infraction should compulsorily lead to prosecution. On this reasoning, the Court quashed Madhubani Town P.S. Case No. 265 of 2020 and all other prosecutions arising from it against the petitioners. Both writ applications were allowed.
Why This Judgment Matters
This judgment is important for manufacturers, distributors and shopkeepers dealing in non-alcoholic beverages in Bihar under prohibition.
The Patna High Court has made it clear that prosecution under the Bihar Prohibition and Excise Act, 2016 cannot be launched merely because a lab report shows a slightly higher alcohol content in a non-alcoholic drink, without proof that the product is sold or used as an intoxicant.
The Court also highlighted that authorities must follow proper BIS and FSSAI testing standards before treating any lab report as the final word. A single, questionable test report is not enough to criminally prosecute manufacturers and traders who hold valid licences and follow regulatory standards.
For ordinary traders and small shop owners in Bihar, this decision signals that bona fide business in non-alcoholic beverages, carried out with proper licences, should not ordinarily invite criminal cases under prohibition law, especially when products conform to recognised standards.
Legal Issues and Answers
- Issue: Can a manufacturer and distributor of malt-based non-alcoholic beverages be prosecuted under the Bihar Prohibition and Excise Act, 2016 and the Indian Penal Code solely on the basis of a single Excise laboratory report showing 0.8% v/v ethyl alcohol in the product?
Answer: The Patna High Court held that such prosecution is not warranted where the beverage is a non-alcoholic drink, not sold or used as an intoxicant, proper BIS and FSSAI standards and licences exist, and the lab report itself does not conform to prescribed testing methods. - Issue: Do minor variations above the 0.5% v/v tolerance limit in a non-alcoholic beverage automatically attract the penal provisions of the Bihar Prohibition and Excise Act, 2016?
Answer: No. The Court held that a minor infraction in ethyl alcohol content of a non-alcoholic beverage does not offend the object and purpose of the Prohibition Act, and a margin of error is inherent in such strict legislation. - Issue: When can the High Court exercise its power to quash an FIR in such cases?
Answer: Relying on Bhajan Lal and Neeharika Infrastructure, the Court held that where, even accepting the FIR allegations in full, no offence is made out and the prosecution is based on an unreliable lab report, the FIR and all proceedings can be quashed under its writ jurisdiction.
Cases Cited by the Court
- M/s Smart India Marketing v. State of Bihar, Cr. WJC No. 627 of 2017, Patna High Court, judgment dated 05.11.2017.
- State of Haryana & Others v. Bhajan Lal & Others, Supp (1) SCC 335.
- Neeharika Infrastructure Pvt. Ltd. v. State of Maharashtra & Others, 2021 SCC OnLine SC 315.
Case Details
Case Numbers: Criminal Writ Jurisdiction Case No. 89 of 2021; Criminal Writ Jurisdiction Case No. 157 of 2021; arising out of Madhubani Town P.S. Case No. 265 of 2020.
Case Titles: United Breweries Limited v. The State of Bihar & Ors; Mukesh Kumar v. The State of Bihar & Ors.
Coram: Hon’ble Mr. Justice Ashutosh Kumar.
Date of Judgment: 09.02.2022.
Citation: 2022 (1) PLJR 787.
Advocates: For the petitioners in both writ cases: Mr. Satyabir Bharti, Advocate; Mr. Avinash Shekhar, Advocate. For the State: Mr. P.K. Verma, AAG.
Nature of the Case: Criminal writ petitions seeking quashing of FIR and criminal prosecution under the Bihar Prohibition and Excise Act, 2016 and the Indian Penal Code.
Link to Judgment: Patna High Court judgment link
If you found this explanation helpful and wish to stay informed about how legal developments may affect your rights in Bihar, you may consider following Samvida Law Associates for more updates.







