
Case Background
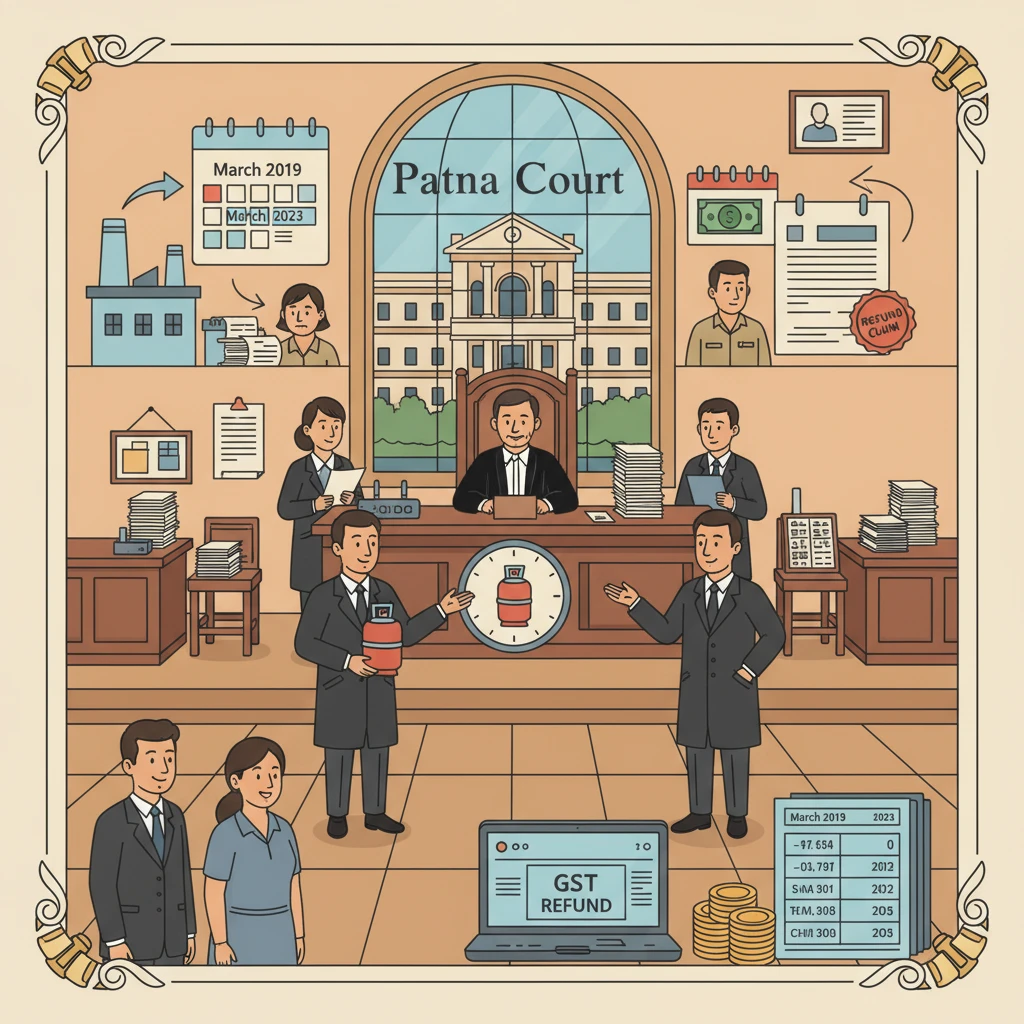
The petitioner is a private company engaged in bottling of LPG at Motihari in East Champaran, Bihar. It purchases LPG in bulk after paying the applicable GST. The LPG is then bottled in cylinders and sold to commercial users at the same tax rate as purchase, and to domestic users at a lower tax rate.
Because of this difference, the petitioner’s input tax (tax paid on purchase) was higher than the tax collected on many of its outward supplies, especially to domestic consumers. This is commonly called an “inverted duty structure”. Under Section 54(3)(ii) of the Central Goods and Services Tax Act, 2017, read with Rule 89(5) of the Central Goods and Services Tax Rules, 2017, such excess input tax is normally refundable.
The relevant period in dispute is the financial year 2018–2019, specifically from October 2018 to March 2019. For this period, the law required that any refund application be filed within two years from the “relevant date”. Under Explanation (2)(a) to Section 54, for refund of unutilised input tax credit, the relevant date is the end of the financial year in which the refund claim arises.
Therefore, for financial year 2018–2019, the relevant date was 31.03.2019 and the normal limitation period for seeking refund expired on 31.03.2021. The Central Board of Indirect Taxes and Customs (CBIC), by Notification No. 13/2022–Central Tax dated 05.07.2022, further extended the time for filing refund claims for that year till 31.03.2023.
During this period, an assessment was carried out for the petitioner for financial years 2018–2019 and 2019–2020. A demand order was raised on 29.01.2021. On 20.03.2021, before the original limitation period for refund expired, amounts lying in the petitioner’s credit ledger—being the unutilised input tax credit under the inverted duty structure—were set off against this demand.
The petitioner alleged before the Court that the Assessing Officer had demanded a bribe and, after the petitioner refused, raised demands far in excess of what was actually due for 2018–2019 and 2019–2020. Copies of the demand orders and the ledger showing recovery from the credit ledger were produced as Annexure-P/6 series. The Court, however, decided the matter on the basis of limitation and statutory provisions and did not adjudicate the bribery allegation.
The petitioner challenged the assessment by filing an appeal. The Appellate Authority, by order dated 20.02.2022 (Annexure-P/7 series), allowed the appeal and ordered that the amounts earlier recovered be credited back to the petitioner’s credit ledger. This credit was actually given back only on 24.08.2022.
According to the petitioner, the appellate order, though dated 20.02.2022, was received only on 15.08.2022, about six months later. The petitioner contended that the limitation period for filing refund should start from this date of receipt of the appellate order.
On 12.04.2023, the petitioner filed an online refund application in Form GST RFD-01 under Section 54 and Rule 89, claiming refund of Rs. 6,12,487/- under IGST for the period in question. This application (Annexure-P/3) was much beyond the original two-year limitation and even beyond the extended date of 31.03.2023 by a few days. The Assessing Officer (6th respondent) issued a notice (Annexure-P/4) stating that the refund application was time-barred.
The petitioner replied (Annexure-P/5), relying on the appellate order and the date of its receipt. In addition to the earlier application, the petitioner filed another physical application for refund (Annexure-P/13) for the amounts that had been set off from the credit ledger against the demands for 2018–2019 and 2019–2020 but were later credited back after the appeal.
What the Court Examined and Decided
The Patna High Court, speaking through Hon’ble the Chief Justice, examined the scheme of Section 54 of the CGST Act and the factual chronology. The key question was whether the petitioner’s refund claim could still be entertained despite the lapse of the normal two-year period for refund of unutilised input tax credit under an inverted duty structure.
First, the Court noted that Section 54 bears the heading “Refund of tax”. Sub-section (1) provides for refund of any tax paid in excess, subject to an application being filed within two years from the relevant date, in the prescribed form and manner. Sub-section (3), read with Rule 89(5), specifically enables refund of unutilised input tax credit in cases of inverted duty structure.
For such inverted duty refunds, Explanation (2)(a) defines the relevant date as the end of the financial year in which the refund claim arises. Applying this, the Court held that for assessment year 2018–2019, the relevant date was 31.03.2019, and the limitation expired on 31.03.2021.
The Court also took note of the CBIC Notification No. 13/2022–Central Tax dated 05.07.2022, which extended the time for filing refund claims for the financial year 2018–2019 till 31.03.2023. Even considering this extension, the petitioner’s online application dated 12.04.2023 was beyond the extended deadline.
On this basis alone, a normal claim for refund of unutilised input tax credit under the inverted duty structure would have been time-barred. However, the Court found that the petitioner’s case had a “peculiar” set of facts that changed the legal position.
By 20.03.2021, before the expiry of the original limitation, the amounts standing in the petitioner’s credit ledger as unutilised input tax credit had already been set off against the demands raised in the assessment for 2018–2019 and 2019–2020. Because of this set-off, there was no remaining balance in the credit ledger that could be treated as inverted duty for the purpose of refund.
The Court observed that when the amount in the credit ledger was set off against the demand, the nature of that amount changed. It was no longer a simple credit lying in the ledger; it became tax recovered by the department pursuant to the assessment order.
Later, when the petitioner’s appeal was allowed on 20.02.2022 and communicated on 15.08.2022, the department credited back the recovered amount to the petitioner’s ledger on 24.08.2022. The Court treated this amount, now in the ledger, as “tax recovered” which had become refundable due to the appellate order, and not as ordinary inverted duty credit.
At this stage, the Court turned to another provision of Section 54. Clause (2) of the second Explanation to Section 54 states that when tax becomes refundable as a result of any judgment, decree, order or direction of an Appellate Authority, the relevant date for computing limitation is the date of communication of such judgment, decree, order or direction.
Applying this clause, the Court held that in the present case, the relevant date was 15.08.2022, the date on which the appellate order was received/communicated. The petitioner’s refund application seeking refund of the amounts credited back to the ledger following the appellate order was therefore governed by this “judgment-based” relevant date, not by the original financial year-based date under Explanation (2)(a).
In other words, once the assessment demand was set off against the credit ledger and later reversed by the Appellate Authority, the refund claim could not be treated as a simple inverted duty refund under Section 54(3). Instead, it became a refund claim of tax recovered and subsequently made refundable by the appellate order, attracting Explanation (2)(e) [described by the Court as Clause (2) of the second Explanation].
On this reasoning, the Court held that the refund application for the tax credited back to the ledger was “perfectly in order”. It directed that refund must be made of the amounts that had been set off from the credit ledger as tax due on the enhanced demands for assessment years 2018–2019 and 2019–2020, which now stood reversed by the appellate order.
The Court also addressed a practical issue: the petitioner’s online refund application had not been uploaded on the GST portal. The State’s counsel submitted that uploading was not possible because the system allowed inverted duty refunds only within two years.
The Court reiterated that, in the present case, the amount in question was not being refunded as inverted duty credit. It had lost that character when it was adjusted against the assessment demand and had to be treated as tax recovered and later refunded on the basis of an appellate order.
Accordingly, the Court held that the petitioner’s physical refund application must be treated under Clause (2) of the second Explanation to Section 54. It directed the authorities to consider this physical application and process the refund within two months from the date the certified copy of the judgment is received.
Finally, the writ petition was allowed with the above directions. The Court did not go into the bribery allegation in detail, as the relief could be granted on the statutory interpretation of Section 54 and the effect of the appellate order.
Why This Judgment Matters
This judgment is significant for businesses and professionals dealing with GST refunds, especially in cases where credit is first adjusted against a disputed demand and later restored after appeal.
The Patna High Court clarified that once input tax credit is set off against a demand, it ceases to be mere “inverted duty credit” and becomes “tax recovered” by the department. If that recovery is later reversed by an appellate order, a fresh right to refund arises from the date the appellate order is communicated.
This means that assessees who win on appeal are not automatically barred by the original two-year limit for inverted duty refunds. They can seek refund of the recovered tax by relying on the special rule in Section 54 that treats the appellate order’s communication date as the new starting point.
The judgment also recognises practical problems with online filing. Where the GST portal does not allow a particular type of refund filing due to time restrictions, a physical application can be considered, provided the case falls under the category of tax becoming refundable due to an appellate order.
Legal Issues and Answers
- Issue: Whether a GST refund claim relating to an inverted duty structure is time-barred when the input tax credit was earlier set off against a demand and later restored after the assessee’s appeal was allowed.
Answer: No. Once the credit was set off, it became tax recovered by the department. After the appellate order, the tax became refundable, and the relevant date for limitation is the date of communication of that appellate order under Clause (2) of the second Explanation to Section 54. - Issue: Can the department refuse to entertain a refund application merely because the online GST portal does not permit filing beyond two years for inverted duty refunds?
Answer: No. In such circumstances, where the amount is tax refundable due to an appellate order and not a standard inverted duty refund, the physical application must be considered under the appropriate clause of Section 54’s Explanation. - Issue: What relief was finally granted to the petitioner?
Answer: The Patna High Court allowed the writ petition and directed refund of the amounts earlier set off from the credit ledger as tax due for assessment years 2018–2019 and 2019–2020, to be effected within two months of receipt of the certified copy of the judgment.
Cases Cited by the Court
- No earlier judicial decisions are expressly cited or relied upon in the text of this judgment.
Case Details
Case Number: Civil Writ Jurisdiction Case No. 18609 of 2023
Case Title: M/s Induvarna LPG Bottling Private Limited v. Union of India & Ors.
Court: High Court of Judicature at Patna
Coram: Hon’ble the Chief Justice; Hon’ble Mr. Justice Harish Kumar
Date of Judgment: 29.02.2024
Citation: 2024 (4) PLJR 898
Advocates for Petitioner: Mr. Sriram Krishna, Advocate; Mr. Akash Chaturvedi, Advocate; Mr. Vijay Kumar Singh, Advocate
Advocates for Union of India: Dr. K.N. Singh, Additional Solicitor General; Mr. Anshuman Singh, Sr. Standing Counsel, CGST & CX
Advocates for State of Bihar: Mr. Vikash Kumar, Standing Counsel-11; Mr. Raghwanand, Government Advocate-11; Mr. Pratik Kumar, Advocate
Nature of the Case: Writ petition seeking refund of GST (IGST) under Section 54 of the CGST Act in the context of an inverted duty structure and subsequent appellate proceedings.
Link to Judgment: https://patnahighcourt.gov.in/viewjudgment/MTUjMTg2MDkjMjAyMyMxI04=-IEs2BBBSkPk=
If you found this explanation helpful and wish to stay informed about
how legal developments may affect your rights in Bihar,
you may consider following Samvida Law Associates for more updates.







