
Case Background
The petitioner joined government service on 10.05.1985 as a Clerk-cum-Accountant under the Adult Education-cum-Non-formal Education project of the Education Department, Government of Bihar.
In this scheme, expenses were shared by the Central and State Governments. Later, the Central Government decided to close the Non Formal Education Programme. As a result, the petitioner and others working under the programme were retrenched with effect from 01.04.2001.
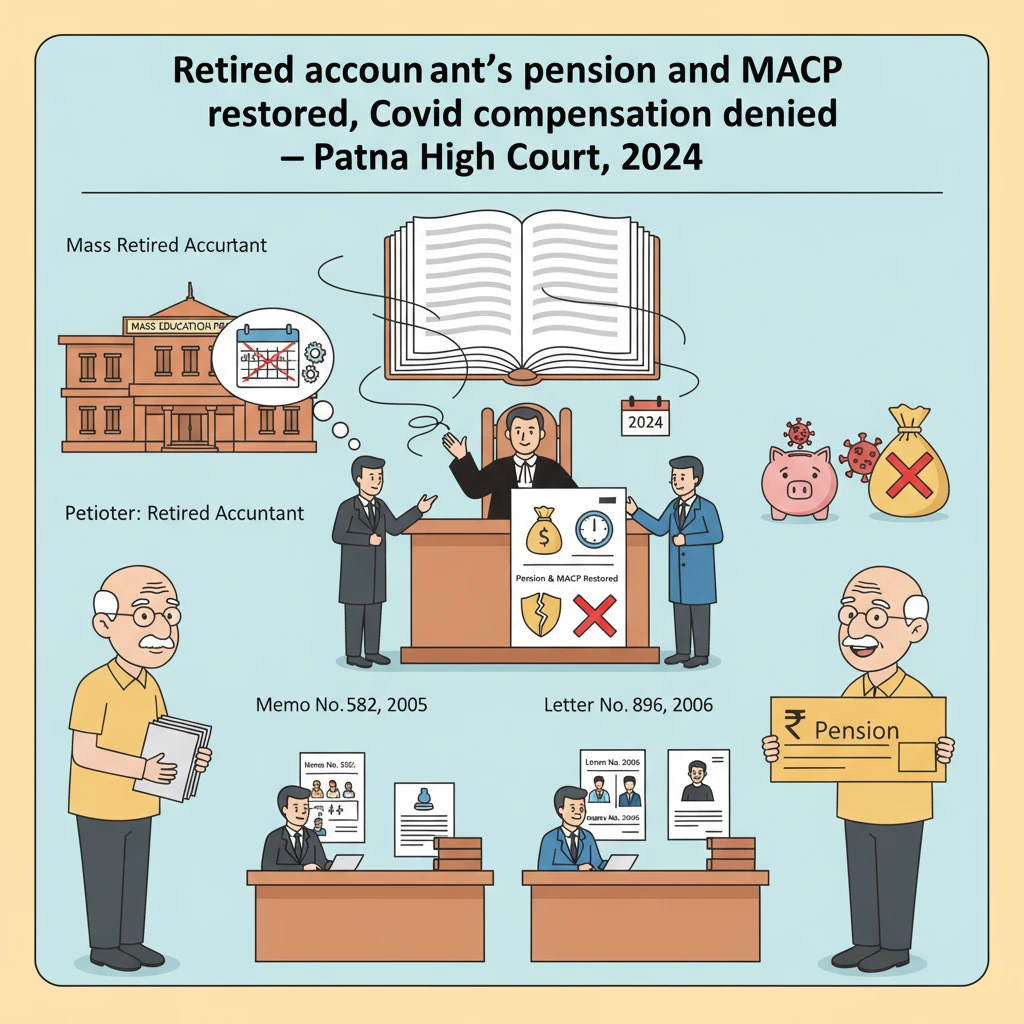
After several judgments of the Patna High Court on the rights of retrenched and surplus employees of Adult Education, the State issued a policy resolution (Memo No. 582 dated 20.05.2005). Under this policy, retrenched employees were to be adjusted in different state departments.
On this basis, the Director, Mass Education, Bihar, by letter no. 433 dated 10.02.2006, recommended that the petitioner be adjusted in the Education Department as an Accountant in the pay scale of Rs. 4000–6000. The recommendation clearly stated that such adjustment would be treated as a new appointment, with no seniority from earlier service, though past service would count for pension.
Following this, the Director (Education) issued office order Memo No. 896 dated 18.04.2006, absorbing the petitioner on the post of Clerk-cum-Accountant in the Education Department.
Here an important difference arose. While the policy and recommendation said adjustment would be a “new appointment”, Memo No. 896 dated 18.04.2006, as issued to the petitioner, stated that his appointment would not be treated as a new appointment. At the same time, it also repeated that his prior service would not be counted for seniority but would count for pension.
The petitioner continued in service and retired on 31.01.2021 from the post of Accountant. At the time of retirement, as per his Last Pay Certificate (Annexure P/6), his last pay drawn was Rs. 76,500/-.
However, his retiral benefits were not released. This led him to file the present writ petition in 2022 seeking release of his retiral dues (except GIC and GPF) with statutory interest, and also Rs. 1,00,00,000/- as compensation for the death of his wife, which he linked to lack of funds for medical treatment during the Covid-19 pandemic.
During the pendency of the case, the Education Department issued orders re-fixing his pay and withdrawing MACP benefits. Therefore, by order dated 05.09.2023, the High Court allowed the petitioner to amend his writ petition and challenge these fresh orders.
What the Court Examined and Decided
Justice Harish Kumar heard counsel for the petitioner and the State. The main dispute revolved around three broad areas:
first, how the petitioner’s past service before retrenchment should be treated for pay and pension purposes; second, whether the Department could reduce his last pay and withdraw ACP/MACP benefits after his retirement; and third, whether he was entitled to Rs. 1 crore compensation for his wife’s death during the pandemic.
Petitioner’s side of the story
The petitioner argued that Memo No. 896 dated 18.04.2006 clearly said his appointment after retrenchment was not to be treated as a new appointment. On this basis, his entire subsequent service was treated as continuous, and his pay had been fixed accordingly.
He pointed out that on the date of his retrenchment (31.03.2001) he was drawing Rs. 5,800/- in the pay scale of Rs. 4,500–7,000/- w.e.f. 01.01.1996. This pay had been duly approved by the Finance Department and entered in his service book, based on letter no. 1129 dated 04.07.2006.
He contended that his pay was correctly fixed and that he had been legitimately granted MACP benefits earlier. Suddenly, after his retirement, the Department treated him as a “new appointee”, reduced his pay and withdrew MACP benefits, which he said was arbitrary and illegal.
Specifically, the petitioner complained that:
- His last pay was first amended from Rs. 76,500/- to Rs. 68,000/- by treating him as a new appointee.
- The Department later issued a corrigendum letter no. 957 dated 27.06.2022, modifying Memo No. 896 dated 18.04.2006 to say his services would be treated as a new appointment.
- By Memo No. 1309 dated 24.07.2023, his MACP benefits, earlier granted w.e.f. 14.02.2005 in Level–V, were withdrawn.
- After withdrawing MACP, his last pay was again re-fixed to Rs. 41,600/-.
The petitioner said this double re-fixation of his pay was done with an ulterior motive to deprive him of 2nd and 3rd MACP.
He also argued that other similarly placed retrenched employees had been paid salary for the retrenchment period, citing information obtained under the Right to Information Act (Annexure P/5). In particular, he pointed to the case of one Smt. Ram Laxmi Mishra, also an Accountant, who had been given salary for the retrenched period and ACP/MACP benefits. The petitioner relied on orders of the Patna High Court and the Supreme Court which had been followed in such cases.
To support parity in ACP/MACP benefits, he relied on three decisions of the Patna High Court:
Ram Naresh Ishwar vs. State of Bihar & Ors. (CWJC No. 17137 of 2009); Bipin Bihari Roy vs. State of Bihar & Ors. (CWJC No. 11936 of 2011); and State of Bihar & Ors. vs. Prabhakar Mishra & Ors. (L.P.A. No. 438 of 2017).
State’s defence
The State’s counsel argued that the petitioner’s original service was under the Non Formal Education Programme, a scheme jointly funded by the Central and State Governments. When the Central Government decided to stop the programme, the petitioner and others were validly retrenched from 01.04.2001.
The State’s policy resolution dated 20.05.2005 (Memo No. 582) clearly provided that adjustment of retrenched employees would be treated as new employment. They would not get seniority based on earlier service; that period would only be counted for pensionary benefits.
Accordingly, the Director, Mass Education, in letter no. 433 dated 10.02.2006, recommended the petitioner for appointment as an Accountant in the pay scale of Rs. 4000–6000/- as a new appointment. Clause (V) of the policy and the recommendation both reflected this.
The State admitted that while implementing this policy, a “typographical mistake” occurred in Memo No. 896 dated 18.04.2006, where it was wrongly written that the appointment would not be treated as new appointment. Clause 2 of the same memo, however, correctly stated that the petitioner would not get seniority benefit for his earlier service.
Once this error was detected, the Department issued letter no. 957 dated 27.06.2022 to correct the appointment letter and align it with the policy decision and recommendation. The State maintained that this was only a correction of an obvious mistake.
The State further relied on the Supreme Court judgment in Civil Appeal No. 10806 of 2018, State of Bihar & Ors. vs. Baliram Singh & Ors. There, the Supreme Court held that readjustment of retrenched employees under the 20.05.2005 policy was to be treated as fresh appointment, and past service could be counted only for pension. The Court noted that those employees had not challenged either the retrenchment order or the policy terms.
The State said the petitioner here had also never challenged his retrenchment or the policy resolution. Therefore, his case was governed by Baliram Singh. After this Supreme Court ruling, the State, by Departmental letter no. 464 dated 28.02.2019, informed the Accountant General that retrenched employees of Formal Education would not get any financial benefit for the period 2001 to 2006–07.
On that basis, the Government re-determined the petitioner’s pay by treating his appointment from 14.02.2006 in the scale of Rs. 4000–6000/- and granting him only 1st ACP w.e.f. 14.02.2016. His pay up to retirement was redetermined by Memo No. 1548 dated 01.09.2023.
The State also cited a Patna High Court decision in Chharpan Ram vs. State of Bihar & Ors. (CWJC No. 10282 of 2020, decided on 08.07.2022), where it was held that for ACP/MACP purposes, benefits should not be calculated for the period prior to retrenchment.
Court’s analysis on appointment, past service and pension
The Court first examined the policy resolution dated 20.05.2005 and found that Clause (k) provided that retrenched employees would be adjusted on the same salary as at the time of retrenchment. If posts were unavailable, they could be adjusted at minimum salary with written consent.
Clause (V) of the policy clearly stated that such adjustment would be treated as a new appointment. The employees would not get seniority based on their earlier service, but that period would be used for pension purposes.
The Court noted that the Director, Mass Education’s letter no. 433 dated 10.02.2006 followed this policy and recommended the petitioner’s appointment on the post of Accountant in the scale of Rs. 4000–6000/-, explicitly stating that the adjustment would be deemed to be a new appointment, with no seniority from past service, though past service would count for pension.
However, when the actual appointment letter, Memo No. 896 dated 18.04.2006, was issued, it stated that the appointment would not be treated as a new appointment. At the same time, it maintained that past service would not count for seniority but would count for pension.
The Court accepted that Memo No. 896 was the only document communicated to the petitioner. Therefore, he had no reason or occasion to challenge it, since it was apparently favourable to him.
Yet, the Court stressed it could not ignore the “very basis” of his adjustment—namely the policy resolution and the recommendation letter—which clearly treated adjustment as new appointment. The Court held that the petitioner had never challenged either his retrenchment order or the policy decision or the terms in the recommendation letter which deemed the appointment to be new.
In this background, the Court accepted the State’s stand that describing the appointment in Memo No. 896 as “not a new appointment” was a mistake or typographical error. Thus, the petitioner’s case was covered by the Supreme Court decision in Baliram Singh. As per that judgment, the adjustment or appointment of retrenched employees under the 20.05.2005 scheme had to be treated as fresh appointment, and their past service could be used only for pension, not for other service benefits.
Even so, Justice Harish Kumar recognised that the petitioner’s situation had some “exceptional facts and circumstances”, because his appointment letter specifically said his appointment was not to be treated as new appointment, and the same policy’s Clause (k) mandated adjustment at the same pay at which he was retrenched.
From the material on record, the Court found that before retrenchment on 31.03.2001, the petitioner was drawing Rs. 5,800/- in the pay scale of Rs. 4,500–7,000/- with effect from 01.01.1996. Relying on Clause (k), the Court directed the respondents to re-fix the petitioner’s pension on the basis of basic salary drawn in that pay scale (Rs. 4,500–7,000/-) as on retrenchment, in terms of the policy resolution dated 20.05.2005.
ACP/MACP benefits and re-fixation orders
The Court then turned to the impugned orders—Memo No. 1309 dated 24.07.2023 withdrawing ACP/MACP benefits, and Memo No. 1321 dated 25.07.2023 re-fixing the petitioner’s pay.
It noted that the petitioner’s service prior to retrenchment was already being counted for pension. It was also pointed out at the bar that several other similarly placed employees had been allowed ACP/MACP benefits by counting their past services before retrenchment.
The Court examined its earlier decisions in Ram Naresh Ishwar, Bipin Bihari Roy and Prabhakar Mishra. In these cases, the Court had treated such retrenched and later absorbed employees as forming one class, permanently absorbed against regular sanctioned vacancies. The policy decision and subsequent appointment letters confirmed permanent absorption, pay protection and counting of past service for pension. On that basis, the benefit of ACP/MACP was granted by counting past service.
The Division Bench in Prabhakar Mishra had particularly held that where an employee’s service in a corporation or similar body is absorbed into State Government service upon winding up of that body, and that earlier service is counted for pension, there should be no impediment in counting it for ACP/MACP as well. The Bench clarified that this was different from fresh recruitment by selection.
Following this line of reasoning, Justice Harish Kumar concluded that the petitioner too was entitled to have his ACP/MACP benefits continued, and that the withdrawal of those benefits and consequential re-fixation of pay were unsustainable.
The Court therefore held that Memo No. 1309 dated 24.07.2023 (withdrawing ACP/MACP) and Memo No. 1321 dated 25.07.2023 (re-fixing pay) were fit to be quashed and cancelled, and accordingly set them aside.
Claim for compensation for wife’s Covid-19 death
On the petitioner’s claim of Rs. 1,00,00,000/- compensation for the death of his wife, he had pleaded that he lacked money for her treatment during the pandemic because his retiral dues were not released.
The Court rejected this claim. It found that the wife’s unfortunate demise was due to Covid-19, and that medical survey data showed that during the pandemic, “lacs and lacs” of people had died not because of lack of money but because of large-scale infection, serious complications, low immunity and prolonged illness.
The respondents had also pointed out that the death ratio during the pandemic was higher even among elite and well-off families who had no scarcity of money. The Court accepted this reasoning and held that this was not a case warranting compensation for the petitioner on that ground.
Final directions
The writ petition was allowed “to the extent indicated”. In summary, the Court:
- Directed re-fixation of the petitioner’s pension based on his basic salary of Rs. 5,800/- in the pay scale of Rs. 4,500–7,000/- as on 31.03.2001, in line with the policy resolution dated 20.05.2005.
- Quashed and set aside Memo No. 1309 dated 24.07.2023 (withdrawing ACP/MACP benefits) and Memo No. 1321 dated 25.07.2023 (re-fixing pay).
- Refused to grant Rs. 1,00,00,000/- compensation for the wife’s Covid-related death.
- Directed that the entire exercise in terms of the judgment be completed within eight weeks from receipt/production of a copy of the order.
- Made no order as to costs.
Why This Judgment Matters
This judgment is important for many retrenched employees who were later adjusted in Bihar Government departments under the 20.05.2005 policy, especially those from Adult Education and similar schemes.
First, it clearly recognises that even if such adjustment is treated as fresh appointment, past service must be honoured for pension. Here, the Patna High Court specifically ordered pension to be re-fixed on the basis of the pay that the employee was actually drawing at the time of retrenchment.
Second, the Court protected an employee’s ACP/MACP benefits from being taken away years later, especially after retirement, by relying on earlier High Court precedents that allowed counting of past service for ACP/MACP where absorption was permanent and past service already counted for pension.
Third, the judgment sends a clear signal that government departments cannot casually change appointment terms or reduce pay long after retirement without strong legal basis, particularly where previous letters and policy decisions created a legitimate expectation in favour of the employee.
Finally, the judgment draws a firm line on Covid-19 related compensation claims. It clarifies that mere non-payment of retiral dues, without clear proof of a direct link to the death, will not automatically entitle a person to large compensation from the State when the death was due to a widespread pandemic affecting all sections of society.
Legal Issues and Answers
- Issue: Can the State treat the petitioner’s post-retrenchment adjustment as a fresh appointment and deny him the benefit of his past service for pay and MACP?
Answer: Yes, in principle the adjustment is a fresh appointment under the 20.05.2005 policy and the Supreme Court decision in Baliram Singh. However, in the petitioner’s exceptional facts, his past service must be counted for pension, and ACP/MACP benefits already granted cannot be withdrawn; related re-fixation orders were quashed. - Issue: Is the petitioner entitled to pension re-fixation based on the salary he was drawing at the time of retrenchment?
Answer: Yes. The Court directed re-fixation of his pension on the basis of his pre-retrenchment basic pay of Rs. 5,800/- in the pay scale of Rs. 4,500–7,000/- in terms of Clause (k) of the 20.05.2005 policy resolution. - Issue: Can the petitioner claim Rs. 1,00,00,000/- compensation from the State for his wife’s death during the Covid-19 pandemic, allegedly due to lack of money from unpaid retiral dues?
Answer: No. The Court held that deaths during the pandemic, affecting even well-off sections, cannot be assumed to be due to lack of money, and this was not a case warranting such compensation.
Cases Cited by the Court
- State of Bihar & Ors. vs. Baliram Singh & Ors., Civil Appeal No. 10806 of 2018 (Supreme Court)
- Ram Naresh Ishwar vs. The State of Bihar & Ors., CWJC No. 17137 of 2009 (Patna High Court)
- Bipin Bihari Roy vs. The State of Bihar & Ors., CWJC No. 11936 of 2011 (Patna High Court)
- The State of Bihar & Ors. vs. Prabhakar Mishra & Ors., L.P.A. No. 438 of 2017 (Patna High Court)
- Chharpan Ram vs. State of Bihar & Ors., CWJC No. 10282 of 2020 (Patna High Court)
- Orders in the case of Smt. Ram Laxmi Mishra, including L.P.A. No. 137 of 2006 and SLP (Civil) No. 9401 of 2009 (referred to and distinguished)
Case Details
Case Number: Civil Writ Jurisdiction Case No. 182 of 2022
Case Title: Ujjwal Kant vs. The State of Bihar & Ors.
Coram: Hon’ble Mr. Justice Harish Kumar
Date of Judgment: 08.01.2024
Citation: 2024(1) PLJR 524
Advocates:
- For the petitioner: Mr. Pawan Kumar Choudhary, Advocate; Mr. Manoj Kumar, Advocate
- For the State/Respondents: Mr. Kameshwar Kumar, GP-17; Mr. S. K. Ranjan, AC to GP-17
- For the Accountant General (A & E), Bihar: Mr. Ram Yash Singh, Advocate
Nature of the Case: Writ petition under Article 226 of the Constitution of India challenging non-release of retiral dues, re-fixation of pay, withdrawal of ACP/MACP benefits, and claiming compensation for Covid-19 related death.
Link to Full Judgment: Patna High Court Judgment in CWJC No. 182 of 2022
If you found this explanation helpful and wish to stay informed about
how legal developments may affect your rights in Bihar,
you may consider following Samvida Law Associates for more updates.







